- Blockchain helps businesses share and verify records across different systems.
- Its main benefits include stronger data integrity, transparency, traceability, and easier auditing.
- Smart contracts automate transactions and other processes when predefined conditions are met.
- Blockchain can reduce manual reconciliation and reliance on intermediaries in multi-party transactions.
- Supply chain companies use blockchain to track products and verify their origins.
- Banks and financial institutions can use blockchain to improve settlements and recordkeeping.
- Public, private, consortium, and hybrid blockchains offer different levels of access and control.
- High setup costs, scalability limitations, and regulatory requirements can make implementation challenging.
- Blockchain is increasingly being explored alongside AI and real-world asset tokenization.
- Businesses should identify a practical use case before investing in blockchain development.
Why is Blockchain Important Today?
A few years ago, most businesses treated blockchain like a passing tech trend attached to cryptocurrency. That changed fast. Companies handling payments, logistics, healthcare records, and digital transactions started running into the same problems: fragmented data, slow verification, and systems that were too easy to tamper with when things went wrong.
Blockchain entered the conversation because it solves some of those issues in a very practical way. Instead of relying on one central authority to manage records, blockchain distributes data across connected networks where transactions become easier to verify and much harder to manipulate. That alone has pushed industries like finance, supply chain, and retail to take blockchain adoption seriously.
The interest is not small either. According to Grand View Research, the global blockchain technology market is projected to reach USD 9.06 trillion by 2033, growing at a CAGR of 88.2% from 2026 to 2033. The forecast reflects growing demand for secure transactions, transparent recordkeeping, and blockchain-based business applications.
This growing demand is also why many organizations now work with a blockchain app development company to build systems tailored to their operations rather than relying on outdated infrastructure. The technology itself matters, sure. But for most businesses, the real value comes from what blockchain helps them avoid: fraud, data inconsistencies, delays, and unnecessary intermediaries.
In this guide, we’ll break down the major benefits of blockchain technology, where it’s being used, and why adoption continues to grow across different industries.
What is Blockchain Technology and Why Does it Matter for Businesses?
Most businesses don’t really start with definitions. They usually start with a problem: data that sits in separate systems, gets delayed, or doesn’t match when multiple parties are involved. Blockchain changes are set up by shifting records into a shared system where information isn’t locked inside one central database. This shift becomes important once you start dealing with transactions that need agreement between multiple parties.
How A Distributed Ledger Actually Works?
At its core, blockchain is a distributed ledger system. Instead of storing data in one place, information is spread across multiple connected systems called nodes. Each participant holds the same version of the record, which removes the need for a central authority to constantly verify updates. That shared structure quietly removes a lot of back-and-forth that normally slows down business processes.
Why Blockchain Records Are Hard To Alter?
Once data is added to a blockchain, changing it isn’t straightforward. Each block is connected to the one before it using cryptographic links. If someone tries to modify past data, the chain breaks immediately. This doesn’t make systems perfect, but it does make manipulation extremely difficult in real-world use cases like auditing, tracking, or financial reporting.
How Decentralization Changes Control?
Traditional systems rely on one central point of control. Blockchain distributes that control across the network instead. That change reduces dependency on intermediaries and lowers the chances of mismatched or inconsistent records across systems. It also allows multiple parties to work on the same dataset without constantly checking whether everyone has the latest version.
Why Businesses Actually Care About This Structure?
This is where things become practical. With blockchain in place, businesses typically see:
- fewer reconciliation issues between systems
- faster verification of transactions
- cleaner audit trails for compliance
- smoother collaboration between multiple stakeholders
These improvements are why industries like finance, logistics, healthcare, and supply chain management have started paying attention.
Types of Blockchain Technologies
It is necessary to be familiar with the different types of blockchain technologies before picking out one, as each model provides a different level of transparency, control, and scalability for business use cases.
1. Public Blockchain
They are open networks where any person can take part and check the transactions. They are appropriate to be used for decentralization, transparency, and open digital ecosystems.
2. Private Blockchain
They are permission-based networks controlled by one organization. Enterprises that need privacy, quicker processing, and stricter control are those for which it is perfect.
3. Consortium Blockchain
A consortium is a blockchain type controlled by a group of trusted organizations rather than one entity. Common in finance, supply chain, and healthcare collaborations.
4. Hybrid Blockchain
A hybrid blockchain merges the features of both public and private blockchains, thus enabling the confidential data to stay hidden while some of the information can still be verified.
By understanding the different types of blockchain technologies, companies can create secure, efficient, and technologically advanced blockchain solutions. Without further delay, let’s see what are the main benefits of blockchain technology.
Top Benefits of Blockchain Technology
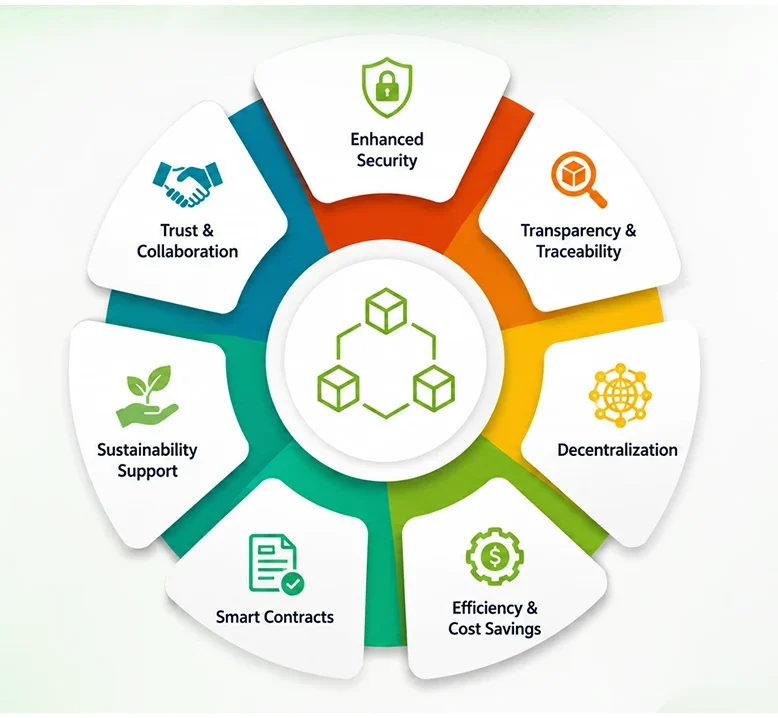
This is the exciting part! These core advantages are why industries are making huge investments in blockchain technology.
1. Enhanced Security And Data Integrity
Security is one of the strongest reasons blockchain gets adopted in enterprise systems. Data isn’t stored in one vulnerable location. It’s distributed across multiple nodes, and every change has to be verified by the network. Once a record is added, it can’t be quietly edited or removed without detection. That makes blockchain useful in environments where data accuracy matters more than convenience. In practice, this reduces fraud risks, unauthorized modifications, and internal data tampering in systems that handle sensitive information.
2. Transparency and Traceability Across Systems
Blockchain creates a shared record of transactions that all authorized participants can view. That changes how tracking works in real operations. Instead of relying on separate logs from different systems, businesses get a single, consistent history of activity. This is especially useful in supply chains where products move through multiple stages and companies. Every step leaves a traceable record, making verification faster and disputes easier to resolve.
3. Reduced Dependencies on Intermediaries
Many traditional systems rely on third parties to validate transactions, approve records, or manage reconciliation between systems. Blockchain reduces that dependency by allowing the network itself to validate transactions through consensus mechanisms. This doesn’t remove trust. It shifts it from institutions to system logic, which often reduces delays and operational friction in multi-party workflows.
4. Faster Transactions and Lower Operational Costs
Without multiple layers of verification and manual reconciliation, transactions move faster. Processes that used to take days can be completed in minutes when blockchain-based systems are properly implemented. From a business perspective, this also reduces operational overhead because fewer intermediaries and manual checks are involved in routine workflows.
5. Smart Contract Automation
Smart contracts are self-executing agreements that run when predefined conditions are met, which is why blockchain in software development keeps growing. There’s no need for manual approval at every step. Once the conditions are satisfied, the system automatically triggers the next action. This is useful in areas like payments, insurance claims, and supplier agreements where timing and accuracy directly impact cost and efficiency.
6. Improved Supply Chain Visibility
Supply chains often suffer from fragmented data across vendors, manufacturers, and distributors. Blockchain helps unify that information into a single shared record that tracks every stage of movement. This makes it easier to verify authenticity, detect inefficiencies, and respond faster when issues occur in logistics or product sourcing.
7. Better Auditability and Compliance Tracking
Regulated industries often struggle with maintaining clear audit trails across systems. Blockchain simplifies this by storing records in a way that is time-stamped, permanent, and verifiable. Auditors don’t need to reconstruct data from multiple sources. The history is already built into the system.
8. Increased Trust in Multi-Party Systems
When multiple organizations share the same system, trust becomes a technical problem, not just a business one. Blockchain helps solve this by ensuring all parties rely on the same verified dataset. This reduces conflicts caused by mismatched records and improves coordination between businesses that don’t fully trust each other by default.
Could Blockchain Solve a Problem in Your Business?
Find out whether blockchain can reduce verification delays, improve traceability, or simplify transactions across your existing business systems.
Explore My Blockchain Use Case!How Different Industries Use Blockchain Technology?
Blockchain in business applications is proving its worth across every major sector.
1. Finance And Banking
Financial systems were among the earliest to adopt blockchain because traditional settlements rely heavily on intermediaries and slow verification cycles. Blockchain improves transaction speed and reduces dependency on multiple layers of approval. Cross-border payments become more predictable, and reconciliation between institutions becomes less complex. This is why many companies involved in fintech app development are integrating blockchain to strengthen transaction security and reduce operational delays.
Key Benefits
- Faster cross-border payments
- Reduced reliance on intermediaries
- Lower transaction reconciliation errors
- Improved fraud detection and audit readiness
2. Supply Chain And Logistics
Supply chains often struggle with fragmented data spread across manufacturers, suppliers, and distributors.
Blockchain creates a unified record of product movement, making it easier to track items from origin to delivery. Each checkpoint is permanently recorded, improving accountability across the entire system.
Key Benefits
- End-to-end product traceability
- Reduced counterfeit risks
- Better coordination between stakeholders
- Faster identification of delays or disruptions
3. Healthcare And Patient Data Management
Healthcare systems deal with sensitive and often fragmented patient data across multiple providers.
Blockchain helps unify records while maintaining strict control over access permissions. This is increasingly relevant in healthcare app development, where secure data sharing between hospitals and labs is a major requirement.
Key Benefits
- Secure and tamper-resistant patient records for HIPAA compliant app development
- Better data sharing between providers
- Reduced duplication of medical histories
- Improved patient data integrity
4. Retail And E-Commerce
Retail operations, including any ecommerce app development company, rely heavily on trust, especially when dealing with product authenticity and delivery tracking.
Blockchain improves transparency across supply chains, allowing customers and businesses to verify product origin and movement history.
Key Benefits
- Improved product authenticity tracking
- Reduced delivery disputes
- Stronger customer trust
- Better supply chain transparency
5. Gaming And Digital Assets
Gaming is moving toward systems where players can have real ownership of in-game assets.
Blockchain enables tokenized assets that can be traded or transferred outside the game ecosystem. This shift is influencing modern mobile game development, especially in games with digital economies and asset-based reward systems.
Key Benefits
- True ownership of in-game assets
- Secure trading of digital items
- Transparent in-game economies
- Enhanced player engagement
6. Government And Public Records
Government systems often deal with challenges around transparency, verification, and record integrity.
Blockchain improves how public data is stored and validated, especially in identity systems, land records, and administrative documentation.
Key Benefits
- Transparent public record systems
- Reduced document tampering risks
- Improved identity verification
- Easier audit and compliance tracking
7. Energy And Sustainability
Energy systems are increasingly exploring blockchain for tracking renewable energy usage and enabling decentralized energy exchange.
It helps improve transparency in carbon tracking and supports peer-to-peer energy trading models.
Key Benefits
- Accurate renewable energy tracking
- Transparent carbon credit reporting
- Peer-to-peer energy trading
- Reduced reporting inconsistencies
Why Businesses Are Investing In Blockchain?
Blockchain adoption is no longer driven by experimentation. Most companies are now focusing on practical outcomes like efficiency, security, and long-term operational stability rather than just testing the technology.
1. Fragmented Systems Are Slowing Businesses Down
Most enterprises still rely on multiple disconnected tools for operations, finance, and data management. The result is duplicated records, delays, and constant reconciliation between systems, a common digital transformation challenge. Blockchain reduces this friction by keeping a shared and consistent version of data across all participants.
2. Security And Compliance Pressure Is Increasing
Data protection and app security best practices are no longer optional. With stricter regulations and more frequent breaches, companies need systems that are harder to manipulate and easier to audit. Blockchain helps by creating records that are transparent, time-stamped, and difficult to alter without detection.
3. Automation Is Becoming A Priority
Businesses are actively trying to reduce manual steps through business process automation in operations like payments, contracts, and logistics. Smart contracts support this shift by automatically executing actions when predefined conditions are met, reducing dependency on human intervention.
4. Multi-Party Trust Needs Are Growing
Modern business ecosystems often involve vendors, partners, and third-party systems that don’t fully trust each other by default. Blockchain reduces the need for repeated verification by maintaining a single shared ledger that all parties can rely on.
5. Demand For Specialized Development Is Rising
This complexity is also why many companies prefer working with a blockchain app development company instead of building solutions in-house. Designing distributed systems requires specialized knowledge that goes beyond traditional custom software development.
Key Drivers Behind Blockchain Adoption
- Stronger Data Security Requirements
- Reduced Operational And Reconciliation Costs
- Faster Cross-Organization Data Sharing
- Increasing Compliance And Audit Demands
- Automation Through Smart Contracts
- Need For Trusted Shared Systems
Need Blockchain to Work With Your Existing Systems?
Explore how blockchain could connect with your ERP, CRM, and business applications without disrupting operations or creating unnecessary technical complexity.
Discuss My Integration Requirements!Implementing Blockchain: What Businesses Should Know
Want to capture the enterprise blockchain benefits? ThesThese are the first steps to create a blockchain app:
- Identify Use Cases: Start with MVP development as a small experiment to validate your mobile app idea. What are the problems with your business, e.g., delays in reconciliation or lack of supply chain transparency, that the technology can solve immediately?
- Choose the Right Platform: Make a choice between a private (Hyperledger Fabric) or a public (Ethereum), and review your mobile app tech stack alongside the structural changes that come with it.
- Design Architecture: In what way will your new system be able to communicate with your ERP, CRM, and databases through backend API development? You cannot afford to have a messy integration.
Pros And Cons Of Blockchain Technology
Blockchain brings clear advantages in transparency, security, and efficiency, but it also comes with practical limitations that businesses need to consider before adoption.
Pros Of Blockchain Technology
1. High Data Security And Integrity
Blockchain records are distributed across a network and protected through cryptographic methods, making unauthorized changes extremely difficult.
2. Greater Transparency Across Systems
All authorized participants can view the same version of data, reducing disputes and improving trust in shared processes.
3. Reduced Operational Costs
By removing unnecessary intermediaries and manual verification steps, businesses can lower overall transaction and processing costs.
4. Faster And More Efficient Workflows
Processes like settlements, approvals, and data reconciliation can move faster when handled through automated blockchain systems.
5. Stronger Trust In Multi-Party Environments
A shared ledger reduces the need for repeated verification between parties that do not fully rely on each other.
Cons Of Blockchain Technology
1. Limited Scalability In Some Networks
Certain blockchain systems can slow down when handling a large volume of transactions.
2. High Initial Setup And Integration Cost
Building or integrating blockchain solutions, including blockchain integration in mobile apps, requires technical expertise and upfront blockchain app development costs.
3. Regulatory Uncertainty In Some Regions
Legal frameworks around blockchain are still evolving in several countries, which can slow adoption, so app development risk management matters.
4. Energy Consumption Concerns
Proof-of-work blockchain networks can consume substantial electricity because they rely on energy-intensive mining. Proof-of-stake networks are generally more energy-efficient.
For example, Ethereum reduced its energy consumption by approximately 99.95% after transitioning to proof-of-stake in September 2022.
5. Complexity Of Implementation
Businesses often need specialized expertise, which adds hidden development costs and is why many rely on external blockchain development teams.
Future Of Blockchain Technology
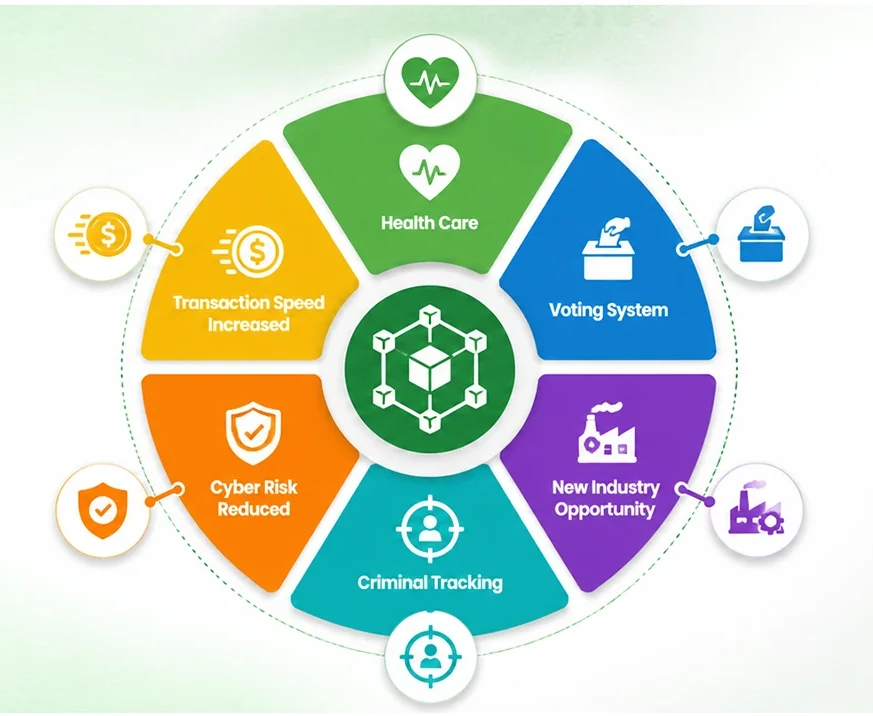
Current blockchain technology trends show that blockchain is not moving in isolation anymore.. It’s starting to merge with other technologies and slowly becoming part of larger enterprise systems rather than a standalone solution.
1. Tokenization Of Real-World Assets Is Expanding
Real estate, financial instruments, and even supply chain assets are being explored in digital token form. This makes ownership easier to divide, transfer, and verify without relying on traditional paperwork-heavy systems.
2. AI And Blockchain Are Starting To Work Together
AI development handles prediction and decision-making, while blockchain provides a verified and tamper-resistant data layer. Together, they are being used to reduce fraud risks, improve automation accuracy, and strengthen data reliability in enterprise systems.
3. Enterprise Adoption Is Becoming More Structured
Earlier blockchain adoption was experimental. Now, companies are focusing on specific use cases like compliance tracking, logistics transparency, and financial settlement systems. The shift is moving from exploration to implementation, guided by a clear product launch strategy.
4. Regulatory Frameworks Are Slowly Maturing
Regulatory frameworks for blockchain-based financial services are becoming more established. The European Union’s Markets in Crypto-Assets Regulation (MiCA) provides a regulatory framework for covered crypto-assets and service providers.
However, requirements still vary across jurisdictions and blockchain use cases, making compliance planning important for businesses entering regulated markets.
5. Integration With Existing Systems Is A Key Focus
Instead of replacing entire infrastructures, blockchain is increasingly being integrated into existing enterprise systems through system integration API automation. This reduces disruption and makes adoption more practical for large organizations.
What Does This Mean For Businesses?
Blockchain is gradually becoming part of normal digital infrastructure and digital product development rather than a separate innovation layer. Businesses that understand how to integrate it into existing workflows are more likely to benefit from efficiency gains and improved data reliability.
Key Takeaways On Blockchain Technology Benefits
Blockchain has steadily moved from an experimental technology into something businesses are actively using to improve how data is stored, shared, and verified. Across industries, its value shows up in more practical ways like reducing reconciliation issues, improving traceability, strengthening security, and making multi-party systems easier to manage. It’s not replacing existing systems overnight, but it is gradually filling the gaps where traditional databases struggle with trust, transparency, and coordination.
For businesses exploring where blockchain actually fits into their operations, the next step usually comes down to implementation choices and use-case clarity, which product strategy consulting or a discovery sprint can provide. This is where many organizations look for guidance through blockchain app development services to understand what can realistically be built and how it would integrate with their current systems without unnecessary complexity.
Build Blockchain Systems That Actually Fit Your Business Needs
Not every workflow needs blockchain, but the right use case can significantly improve security, transparency, and efficiency.
Talk To A Blockchain ExpertFAQs About The Benefits of Blockchain Technology
The biggest advantages of blockchain technology are its security features (secured through permanent records and encryption), absolute transparency for all authorized users, high efficiency as a result of the use of automation, fast settlement, and the generation of trust in multi-party systems.
One of the major reasons that blockchain technology is still very much needed nowadays is that it offers answers to the most fundamental problems of the digital economy, for example, the need for a single source of truth, providing data security without a central authority, and allowing complex legal agreements to be executed automatically through smart contracts.
Yes. Blockchain continues to attract investment, particularly in financial services and enterprise applications. Grand View Research estimates the blockchain technology market will reach USD 108.3 billion in 2026 and projects further growth through 2033. However, adoption depends on implementation costs, regulatory requirements, and whether blockchain offers a clear advantage over existing systems.
The advantages of public blockchain (like Ethereum) include openness (anyone can join), high resilience (no single point of failure), censorship resistance, and the ability to leverage a massive, globally distributed network for transaction validation.
Blockchain can improve customer service by providing transparent, immutable records for product provenance, loyalty points, and delivery tracking. This eliminates disputes and quickly resolves issues by giving both parties a verifiable history.
The benefits of smart contracts include automation (executing agreements automatically), reduced costs (eliminating intermediaries), speed (instant settlements), and trust (ensuring contract terms are executed exactly as coded).
Games need blockchain to provide true digital ownership of in-game assets to players through NFTs. This creates new digital economies, enables secure trading, and ensures transparency and fairness in item drops and asset values.